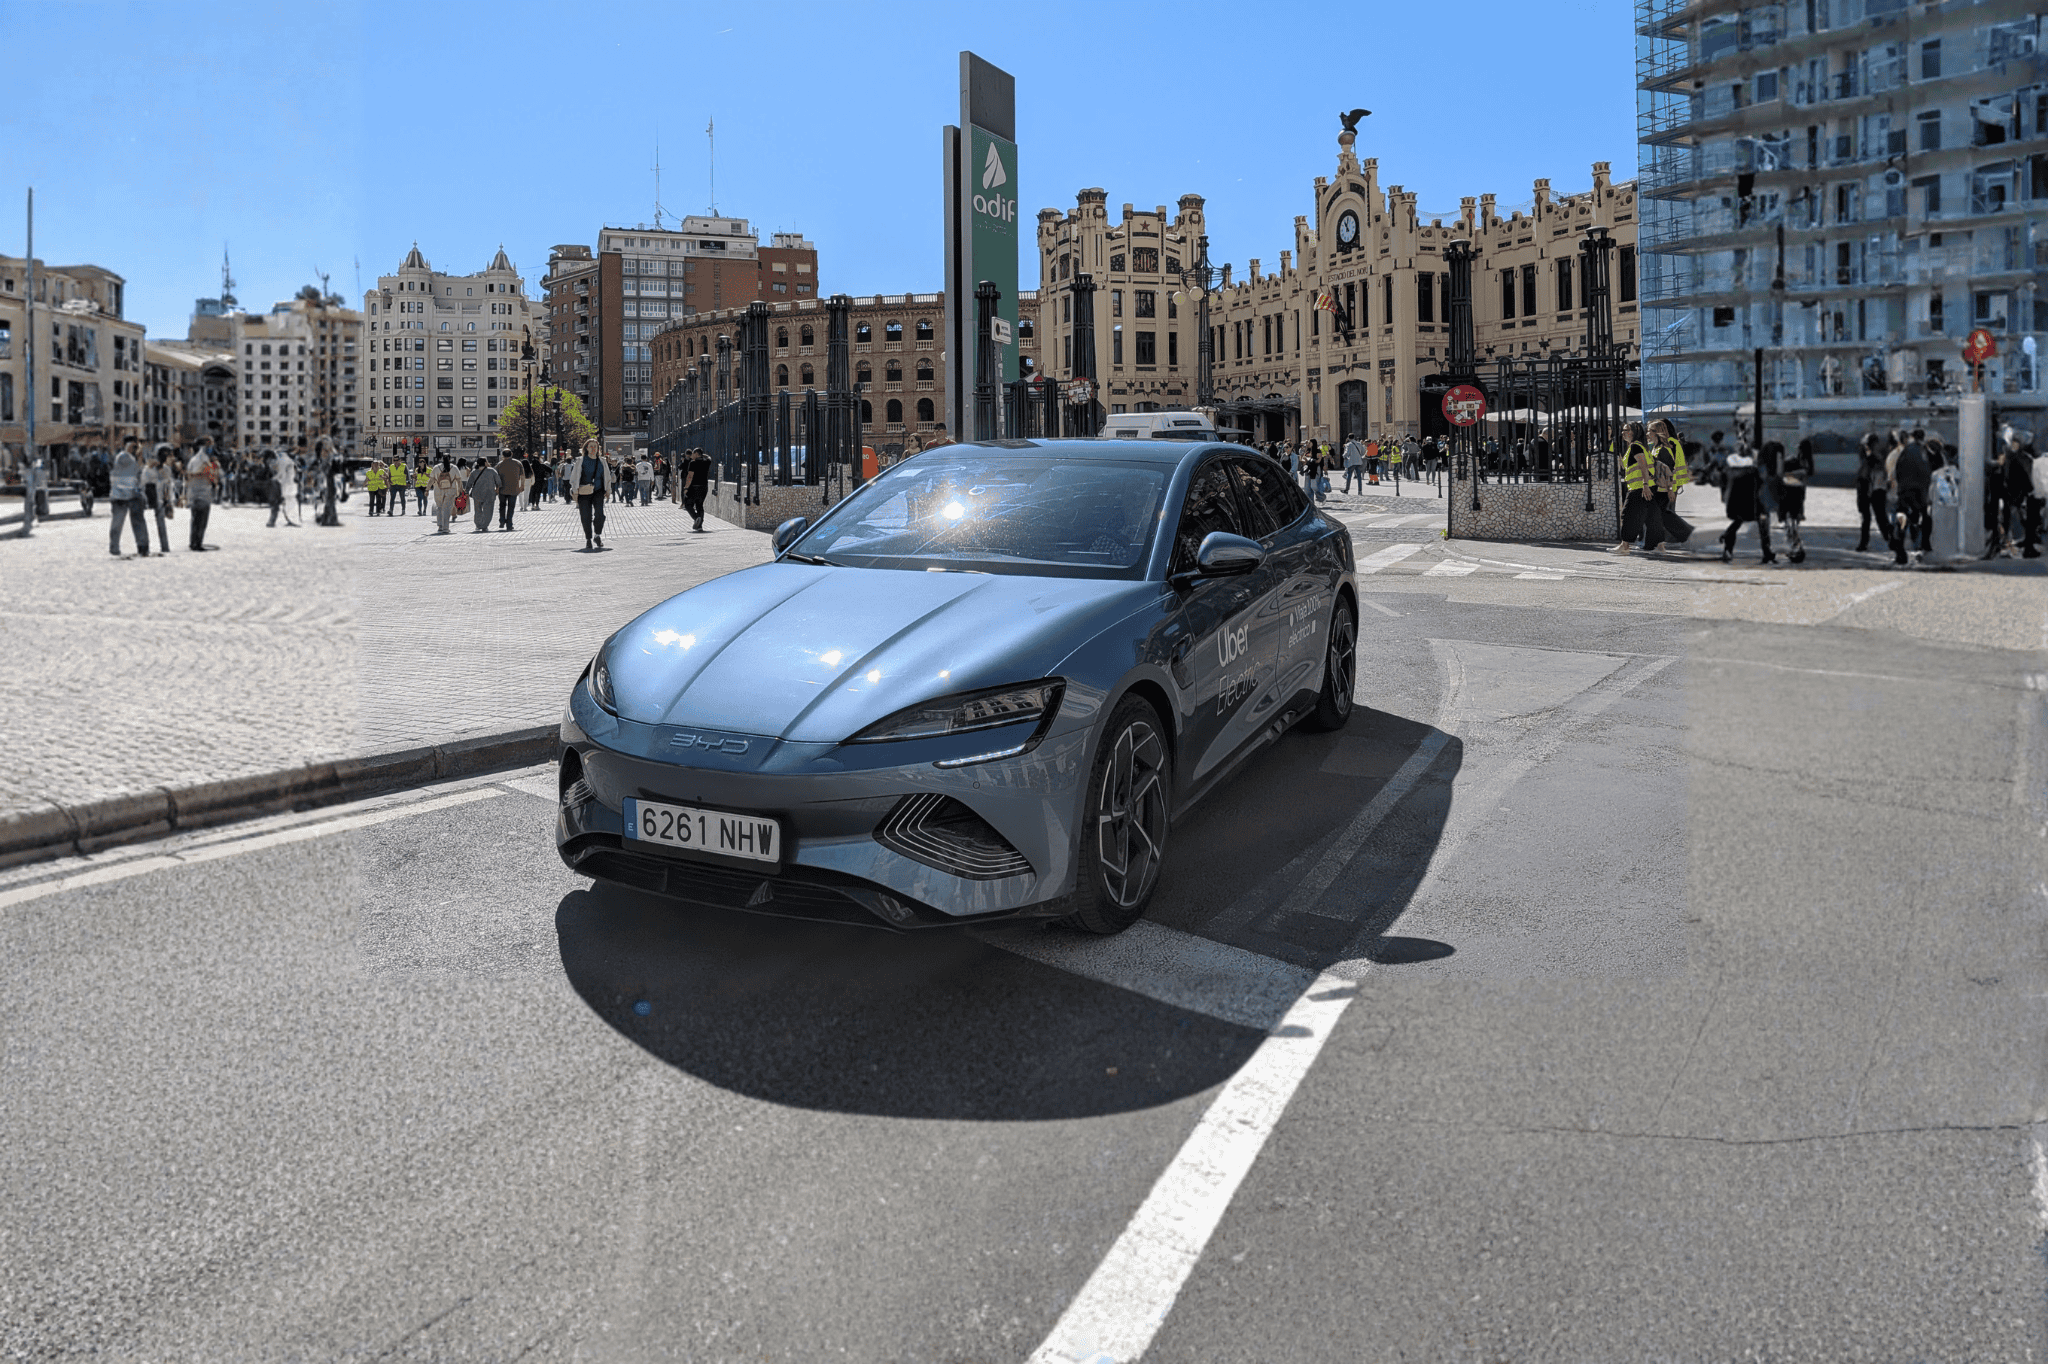
The issuance credit allows the Chinese EV maker to grow quickly while leaving the asset risk to lenders.
This article appears in the July/August issue of Global Finance Magazine.
Walk the streets of cities like Valencia or Paris, and you don't need data to see BYD everywhere, especially on boarded planes and private transport. These days, the sleek logo you recognize doesn't always belong to Tesla or Kia; it is usually BYD.
Sales of BYD's electric vehicles increased significantly across Europe last year, up nearly 270% year-on-year. In the first quarter of 2026, sales increased by another 156%.
While most of the coverage pegs this as a product issue, the bigger issue is financing: BYD's rise has less to do with design or price than with how the cars are financed.
BYD has yet to grow in Europe by building a captive finance arm. Instead, it is directly connected to the region's existing banking and leasing infrastructure, achieving financial inclusion without the burden of a balance sheet. In doing so, it has turned Europe's financial system into an engine for the distribution of cars by turning them into paid goods.
At first glance, BYD's success seems straightforward: strong demand, fast adoption, and the new entrant quickly gets a share. But in a market where cars are often financed, leased, and cycled through multiple stations before reaching long-term ownership, headline numbers don't always tell the whole story. The increase in European BYD registrations may reflect demand and financing capacity, or it may reflect window dressing shaped by the way the system works.
Converting Cars into Collateral
Vehicle Management Center
BYD relies on a simple but smartly implemented set of financing and leasing programs. Cars are sold in bulk to rental companies, car operators, and dealer networks, who then finance or lease them to end users, including corporate customers, ride-hailing drivers, and private buyers. European banks and auto finance platforms provide the underlying credit, while leasing firms create contracts and manage the residual value projections.
What stands out in BYD's case is the speed and scale of operations.
“European OEMs [original equipment manufacturers] they built their captive financial arsenal over 30 to 40 years, and those businesses now operate as profit centers,” said Stefan Bratzel, founder and executive director of the Center of Automotive Management (CAM) in Bergisch Gladbach, Germany.
Instead, he notes, the company is partnering with established financing providers to accelerate market penetration. BYD benefits from “speed to market at the expense of margins while accumulating a balance sheet and regulatory position to eventually internalize these operations.”
In essence, BYD is pushing the decades-long captive financing model into a partner-led model, margin trading and control for quick access to Europe's credit and leasing channels.
It's easy to see the appeal for lenders: Vehicles placed on lease or fleet systems become financial units, combined into loan or lease portfolios that generate predictable cash flows. In a market where electrification is a policy priority and investment theme, high-volume EV systems provide a continuum of assets.
Window Dressing?
The speed of BYD's expansion raises questions about the numbers.
“BYD's channel mix is improving,” said Matthias Schmidt, an independent analyst who tracks the European car market. The share of sales in Germany rose to 32.5% of the volume in the first four months of 2026, compared to 12.4% for the whole of the previous year, which suggests a shift to a balanced sales mix. But the relationship between the registration and the cars actually on the road is not so direct.
“Of the more than 30,472 BYD models registered in Germany since they entered the market in December 2022, only 18,536 are currently on the road,” said Schmidt, suggesting that “after the models are registered, they are then exported to other European markets as used car inventory or back to the European used car establishment that they will do much better in the European market. Rather than what they are, we actually call it window-dressing the data.
In a system driven by leasing, fleet placement, and dealer networks, that gap is unusual. Vehicles can be registered at the station before reaching long-term ownership, and then repositioned for resale, export, or short-term use in all markets. For financial stakeholders, the distinction is important: subscriptions may show momentum, but they do not show continued demand.
What Banks Really Write About
For institutions that partner with BYD and help finance its expansion, the focus is less on BYD's immediate concern – speed to market – and more on how those assets perform over time.
Surplus value assumptions underpin the leasing economy. When cars retain value, the system works: Monthly payments remain competitive, credit risk is contained, and lenders and leasing firms can recycle assets efficiently through secondary markets. If they don't, the economy freezes quickly.
“The EV question of net worth is the single biggest structural challenge in auto finance right now,” Bratzel said. “Whoever solves that problem credibly — whether it's through data, scale, or the balance sheet — will have a huge structural advantage.”
Bratzel points to one potential factor that could shape how banks ultimately value that risk: “Direct integration around the battery – especially the battery cells – can have a positive impact on risk assessment, as this is based on a lot of their data.”
BYD's advantage stems in part from how much of that data it controls. Unlike many automakers that rely on third-party suppliers for key components, the company manufactures its own battery cells and key components of the EV supply chain. That level of direct integration gives BYD clear visibility into battery performance over time, arguably the most important variable in determining how an electric car fares.
BYD's regional distribution of growth in Europe adds another layer.
According to Schmidt, about 70% of Chinese EV registrations in Western Europe in the first half of this year were concentrated in Spain, Italy, and the UK: markets that tend to be more price-sensitive and open to new entrants.
While this does not stop BYD's growth, it does suggest that local financial power is driving growth in terms of consumer demand.
| Native OEM Captive Finance |
BYD's Partner-Led Model |
|---|---|
| Build and run your financial arm |
It uses banks and leasing partners |
| Capital letters are not important commitment |
Down great burden |
| It regulates borrowing and direct leasing |
External sources financial activities |
| It usually takes decades to build |
It can measure immediately |
| It maintains a financial advantage | Margin for speed trading |
| Maximum control | Quick market entry |
What Happens Next
BYD's method works. It took out the slowest part of the car boom – credit creation – while maintaining control over product supply and commercial momentum.
As Bratzel suggests, this is not a permanent structure: It is temporary. It is designed to achieve scale first, and then potentially internal capitalize over time. Meanwhile, European banks and leasing platforms are providing balance sheet support to boost growth.
Schmidt's analysis leaves little ambiguity: Not all growth is created equal. Subscription data may show momentum, but it can also show the strength of channels — fleet placements, vendor lists, rezoning — that add up to real-world demand.
For lenders, the difference is not academic. They do not register to write down. They list residual values, which is where the rubber meets the road.
Over the next two to three years, vehicles that are distributed and financed today will begin to cycle back into the system through lease returns, resale markets, and secondary channels. At that time, the ideas that underpin today's financial models will be tested against real-world market conditions.
But the next phase will be less in terms of volume. Instead it will focus on testing a model that allows BYD to quickly enter Europe. If BYD cars hold their value, the company's partner-led model will look less like a workaround and more like a fast version of what legacy automakers have spent decades building. If net sales weaken, or if much of the growth proves to be channel-driven rather than demand-driven, the financing engine that builds BYD's presence could be hampered.
That's the real question for the bankers: Can BYD's Europe-placed cars keep their value once they're back on the market? Because in a financing-driven system, growth can be established, but the performance of the asset determines whether it will last for a long time.
Rocco Pendola is a contributing writer based in Spain.